The UK fashion and textile industry supports a contribution of about £62 billion to UK GDP and 1.3 million jobs, roughly £1 in every £34 of national gross value added (UKFT Industry Footprint Report). A later Oxford Economics estimate puts it nearer £67.5 billion. Note the basis: those are fashion and textiles combined. The British Fashion Council's narrower fashion-only direct contribution has been reported closer to £21-28 billion, and an earlier version of this article quoted "over £35 billion" to the BFC, which matches neither figure.
What this article covers
This article breaks down the 10 biggest British clothing brands by revenue, with data on history, products, and market position. Plus a manufacturer-group lens on what emerging UK brands can learn from these giants and where Portuguese production fits into modern UK supply chains.
Heads up: We're Portugal Clothing Factory, a group of 80 documented Portuguese clothing factories. Since 2021, we've placed dozens of UK-based brands with Portuguese factories. The sourcing-pattern observations and emerging-brand lessons come from those placements. Currency in GBP per UK convention, with EUR equivalents where relevant.
Key Takeaways
- Burberry leads with £2.42bn in the year to 28 March 2026 (~€2,830M), nearly 2.7x the runner-up Clarks
- Five of the ten brands were founded before 1950, showing the strength of British tradition
- The nine still trading employ roughly 34,000 people between them, summed from their own filings rather than quoted from a trade body
- Footwear carries significant weight: Clarks, Dr. Martens, and Jimmy Choo all on the list
- Most UK brands now source production outside the UK; Portugal is among the fastest-growing nearshoring partners
- UK brands we place typically budget £15,000-£40,000 (~€17,500-€47,000) for a first Portuguese production run, which is a figure from our own quoting rather than a survey
Try it free: Pressure-test your UK-brand production cost with our garment cost calculator before sourcing. 60 seconds, no email required.
Which Are the Biggest UK Clothing Brands by Revenue?
Before diving into each brand, the big picture. The table below summarises the key data for the 10 largest UK clothing brands, ranked by annual revenue.
| Rank | Brand | Founded | Revenue | Period | Employees |
|---|---|---|---|---|---|
| 1 | Burberry | 1856 | £2,420M | FY2026, to 28 Mar 2026 | 8,450 |
| 2 | Clarks | 1825 | £901.3M | Latest filed accounts | 6,161 |
| 3 | Dr. Martens | 1947 | £787.6M | Latest reported year | 2,700 |
| 4 | River Island | 1948 | £701.5M | Pre-restructuring year | 6,751 |
| 5 | Alexander McQueen | 1992 | £670M (estimate) | Not separately disclosed | ~2,000 |
| 6 | Superdry | 2003 | £488.6M | Latest reported year | 2,200 |
| 7 | Jimmy Choo | 1996 | ~£477M (US$605M) | FY2025, to 29 Mar 2025 | ~2,000 |
| 8 | AllSaints | 1994 | £459.5M | Latest filed accounts | 2,400 |
| 9 | Barbour | 1894 | £321.8M | Latest filed accounts | 1,000 |
| — | Ted Baker | 1988 | No UK trading revenue | UK retail closed 2024 | 975 pre-insolvency |
Company annual reports and Companies House filings, as linked in each brand section below. Four corrections against earlier versions of this table. Burberry was given as £2,000.5M; its FY2026 revenue to 28 March 2026 was £2.42bn. Jimmy Choo was given as £618M, which was in fact Capri Holdings' US dollar figure for fiscal 2024; fiscal 2025 was US$605M, roughly £477M, so the brand moves from sixth to seventh. Alexander McQueen is not separately disclosed by Kering, which reports it inside "Other Houses", so its figure is an estimate and labelled as one. Ted Baker is no longer ranked: its UK and European retail arm entered administration in March 2024 and all UK stores closed that autumn.
Fiscal years differ between these companies, so the ranking compares periods that do not align. Treat it as an ordering of scale rather than a like-for-like league table. EUR conversions in the text use £1 to €1.17 and move with the rate.
1. Burberry: Why Does It Lead the Ranking?
With £2.42bn of revenue in the year to 28 March 2026 (about €2,830M) and 8,450 employees, Burberry is far and away the largest British fashion brand by turnover (Burberry Annual Report 25/26). An earlier version of this article gave £2,000.5M, which matches no reported year. Thomas Burberry founded the company in 1856 in Basingstoke, and it's built nearly 170 years of history in the luxury segment.
Thomas Burberry invented gabardine, a waterproof, breathable fabric that transformed outerwear. During World War I, the brand supplied trench coats to the British army. That coat became the house's most iconic product, and it still is today.
Core products and segments
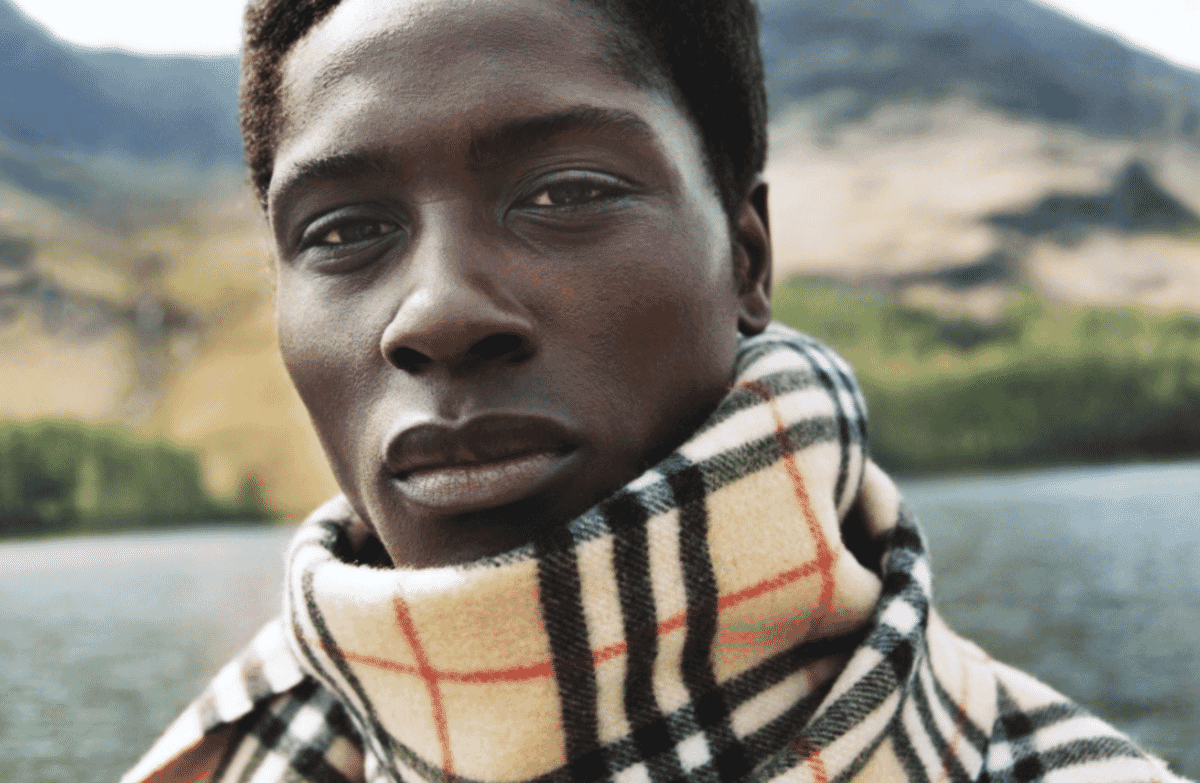
Burberry operates across three segments: accessories, ready-to-wear, and footwear. The beige, black, and red check pattern is recognisable anywhere in the world. The brand runs over 400 own-brand stores across markets including China, the United States, and Europe.
What sets Burberry apart is the combination of artisanal heritage and a strong digital presence. Burberry was one of the first luxury brands to livestream runway shows on social media, a move that helped reshape how high-end fashion connects with younger audiences.
Sourcing pattern
Burberry maintains UK production for its iconic trench coats at the Castleford factory in Yorkshire, but most ready-to-wear is produced in Italy and other EU countries. Portugal is part of Burberry's supply chain for select knitwear and accessories programs.
Citation Capsule: Burberry, founded in 1856, reported £2.42bn of revenue in the year to 28 March 2026, roughly €2,830M, with adjusted operating profit of £160M against £26M the year before. It employs about 8,450 people and is the UK's largest clothing brand by turnover, ahead of Clarks by nearly 2.7x.
2. Clarks: How Does a 200-Year-Old Brand Stay Relevant?
Clarks posts £901.3M (~€1,055M) in revenue and has 6,161 employees, making it the UK's second-largest fashion brand (Clarks Global, 2025). It's also the oldest on this list, founded in 1825 by Cyrus and James Clark in Street, Somerset.
The company started by making slippers from sheepskin. Over two centuries, it evolved into one of the world's biggest footwear brands. The Desert Boot, launched in 1950, remains a timeless classic.
What makes Clarks special
Clarks sells in over 100 countries. Its focus on comfort and durability appeals to a broad audience, from children to adults. In recent years, the brand has invested in more sustainable materials, aligning with the expectations of European consumers.
Is it a fashion brand or a functional footwear company? Both. Clarks manages to balance contemporary design with the practicality that made it famous.
Sourcing pattern
Clarks production sits primarily in Vietnam, India, and Cambodia, with selected European production for premium and heritage lines. UK manufacturing is limited to a small artisanal output for archive and limited-edition pieces.
3. Dr. Martens: What Explains the Cult Following?
Dr. Martens brought in £787.6M (~€922M) in revenue and employs 2,700 people, cementing its position as the UK's third-largest fashion brand (Dr. Martens PLC Annual Report, 2025). Founded in 1947 by Klaus Märtens, the brand was born in Germany but became a British cultural icon.
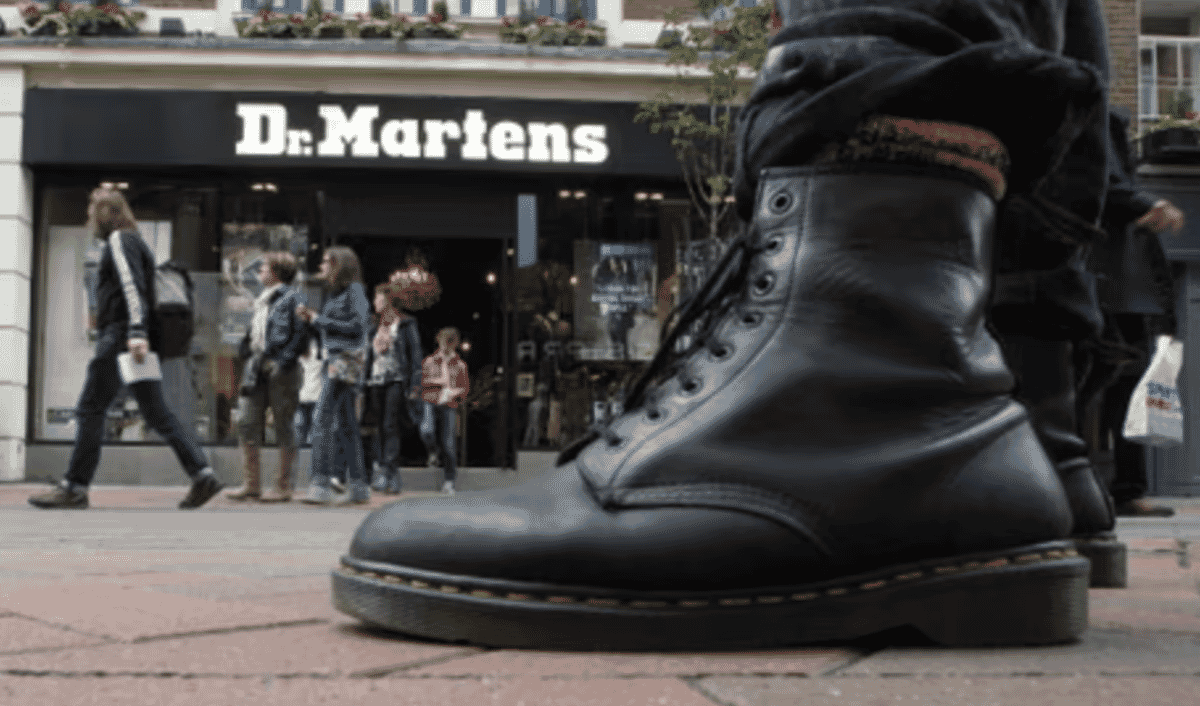
The backstory is fascinating: Märtens, a German doctor, designed a boot with an air-cushioned sole after injuring his foot while skiing. In 1960, the English company R. Griggs bought the patent and launched the iconic 1460, the eight-eyelet boot that changed everything.
Subcultures and identity
Dr. Martens have been adopted by punks, skinheads, grunge fans, and more recently, the mainstream fashion world. They're one of the best examples of how a utilitarian product can take on deep cultural meaning. The brand now sells boots, shoes, and sandals in over 60 countries.
The average price for a pair sits around £150 (~€175). Despite the premium positioning, demand stays high, especially among consumers aged 18 to 35.
Sourcing pattern
Dr. Martens production is primarily in Vietnam and China, with Made in England (MiE) lines produced at the original Cobbs Lane factory in Wollaston, Northamptonshire. The MiE collection commands a 30-50% premium and serves the heritage-conscious customer.
4. River Island: What Went Wrong, and What Went Right?
River Island is the UK's fourth-largest clothing brand here at £701.5M (~€821M) of revenue with 6,751 employees, on filings that predate its restructuring (Companies House). Bernard Lewis founded the chain in 1948 with a single London shop.
River Island has been through a hard two years. It reported a £65.3M operating loss for 2024, then closed 33 stores, negotiated rent reductions across dozens more and brought Ben Lewis back as chief executive, returning to an £11.6M pre-tax profit in 2025. The chain still runs several hundred stores and remains owned by the founding family, which is the thing that let it restructure on its own timetable rather than a shareholder's.
Audience and positioning
The brand sits between pure fast fashion (like Primark) and mid-range labels. Collections are refreshed frequently, keeping pace with runway trends. River Island also runs its own footwear and accessories line.
Family control is the real differentiator, and the 2024-25 restructuring is the clearest demonstration of it. A listed competitor posting a £65M operating loss would have faced a very different set of pressures.
Sourcing pattern
River Island sources primarily from Bangladesh, China, Turkey, and Pakistan, typical for the affordable mid-market positioning. Portugal sourcing has grown for select premium collections and faster-cycle drops.
5. Alexander McQueen: How Big Is It Really?
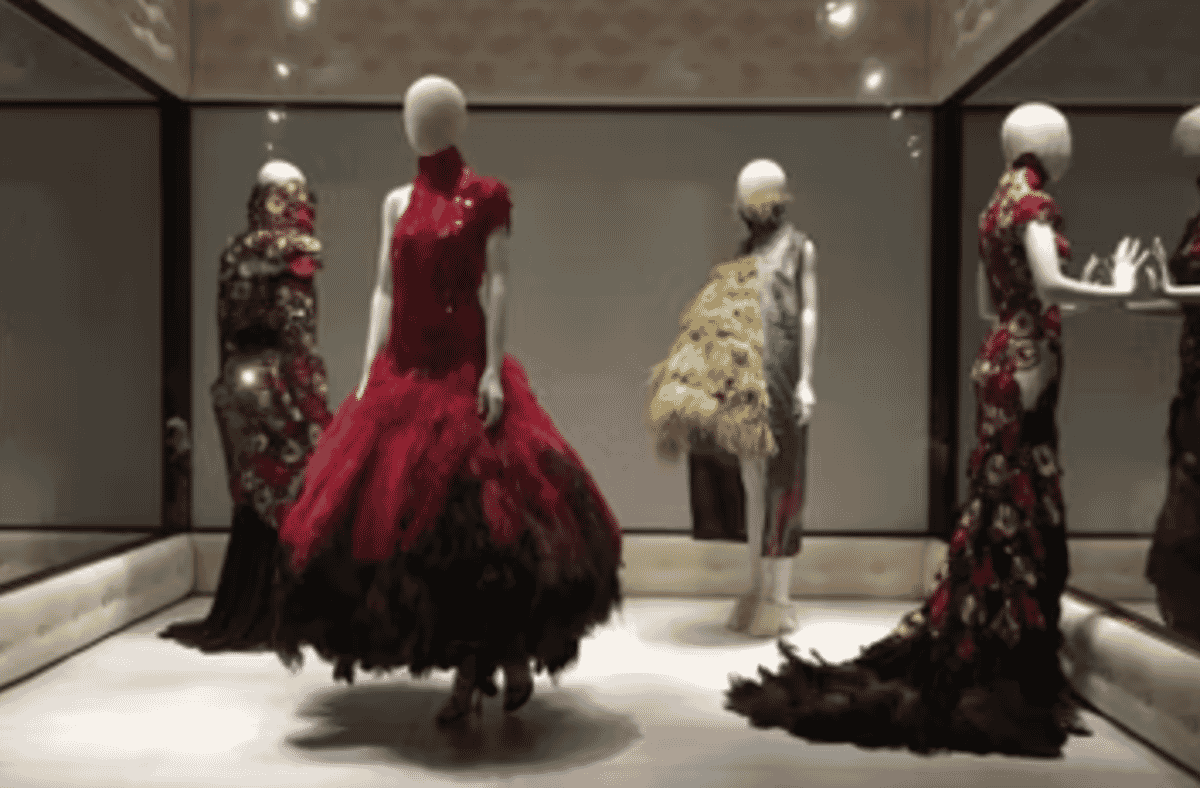
Alexander McQueen is usually put at around £670M (~€784M) of revenue with roughly 2,000 staff, which would make it the fifth largest here. Treat that as an estimate: Kering reports McQueen inside its "Other Houses" segment and does not disclose the brand separately (Kering), so no published figure exists to cite. Lee Alexander McQueen founded the label in 1992 in London and quickly became one of the most provocative designers of his generation.
McQueen was known for theatrical runway shows and pieces that challenged convention. After his death in 2010 creative direction passed to Sarah Burton, who held it until 2023; Sean McGirr has led design since. The house has belonged to the group now called Kering since 2000, when Gucci Group took a controlling stake.
Products and influence
The Oversized Sole trainers became a global phenomenon. The brand operates across ready-to-wear, accessories, and luxury footwear. Tailored pieces remain the heart of the collection.
Sourcing pattern
Alexander McQueen production is primarily Italian (Kering's preferred manufacturing geography), with select pieces produced in the UK and France. Portuguese production appears in selected knitwear and accessories programs across the broader Kering portfolio.
Citation Capsule: Alexander McQueen was founded in London in 1992 and has belonged to the group now called Kering since 2000. Kering reports it within "Other Houses" and does not disclose brand-level revenue, so the figure of roughly £670M that circulates for McQueen is an estimate rather than a reported number. Sarah Burton led design from 2010 to 2023; Sean McGirr has since.
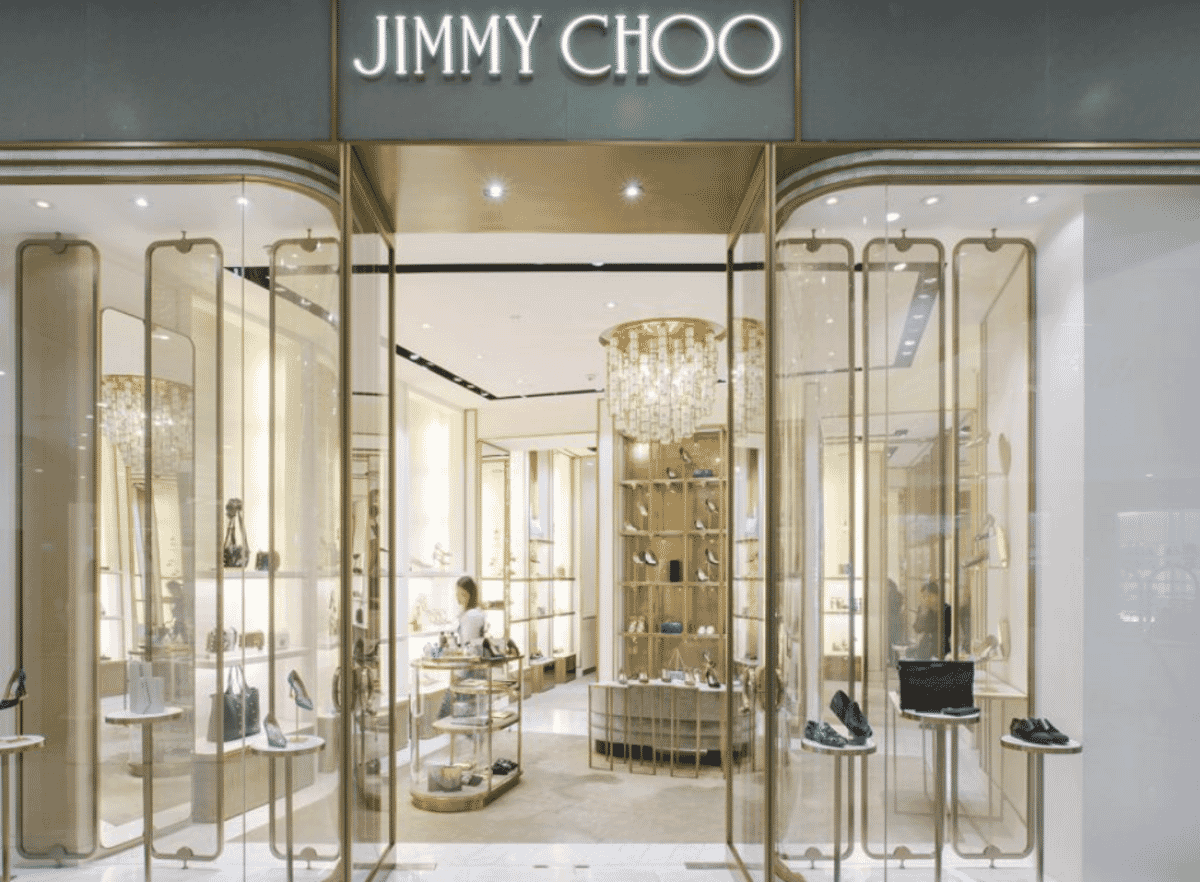
7. Jimmy Choo: Where Are the Shoes Actually Made?
Jimmy Choo reported revenue of US$605M in the fiscal year to 29 March 2025, roughly £477M or €558M, down from US$618M the year before (Capri Holdings, FY2025). That places it seventh rather than sixth: an earlier version of this article reproduced the US dollar figure as if it were pounds, inflating the brand by about 17% and misplacing it in the ranking. Jimmy Choo and Tamara Mellon co-founded the brand in 1996 in London's East End.
Jimmy Choo, a Malaysian-born cobbler based in London, was already making bespoke shoes for Princess Diana. With Tamara Mellon, then an editor at British Vogue, he created one of the world's most coveted luxury footwear brands.
Expansion and products
Today, Jimmy Choo sells shoes, handbags, eyewear, and fragrances. The brand belongs to Capri Holdings (which also owns Versace and Michael Kors). Stilettos remain the house signature, but the luxury trainers line has grown significantly.
Three of the ten brands here, Clarks, Dr. Martens and Jimmy Choo, are primarily footwear businesses. That is a genuine feature of British fashion rather than a quirk of this list: shoemaking is where several of the country's oldest surviving clothing companies began.
Sourcing pattern
Jimmy Choo production is primarily Italian, in line with luxury footwear conventions. UK production is limited to bespoke and archive pieces.
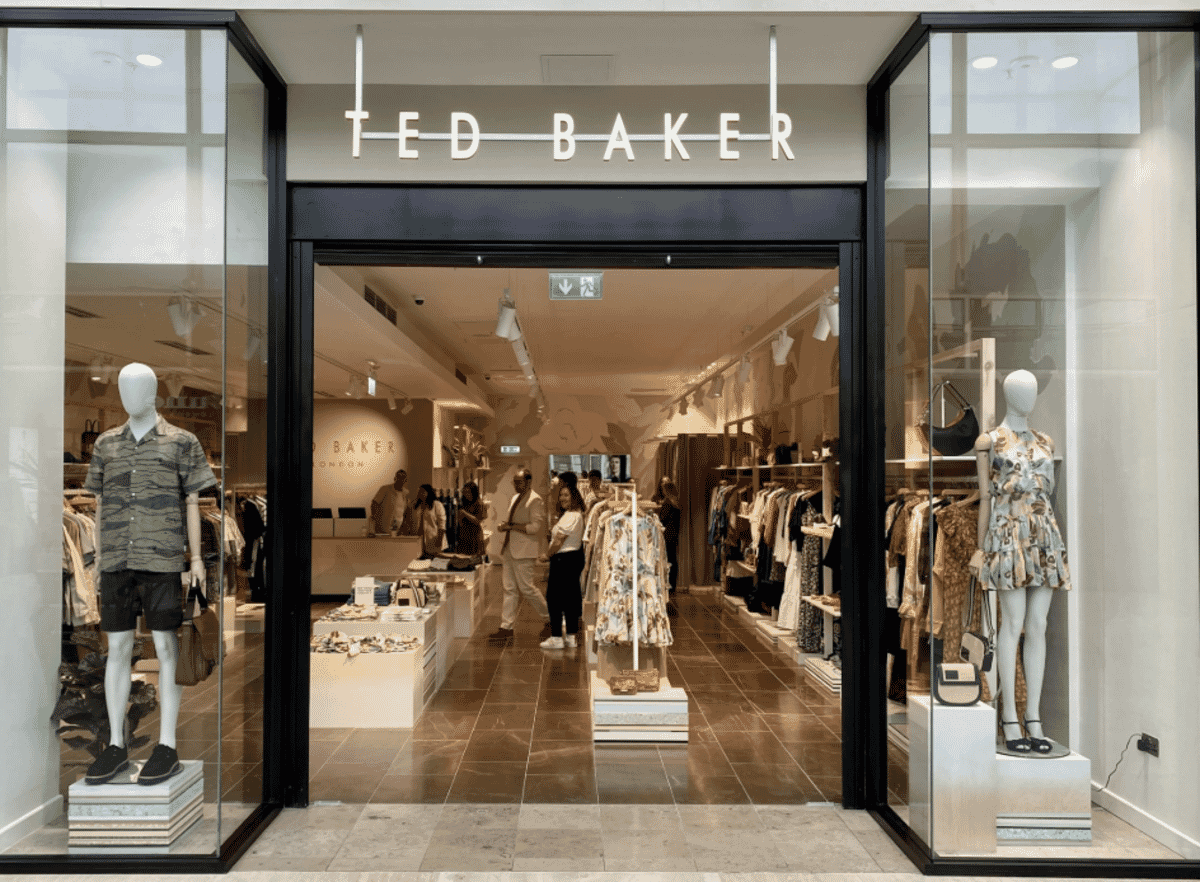
8. Ted Baker: What Happened to It?
Ted Baker is the one entry here that no longer belongs in a revenue ranking, and saying so plainly matters more than keeping the list tidy. No Ordinary Designer Label Limited, which ran Ted Baker's UK and European stores, entered administration in March 2024, and every UK and Ireland store had closed by that autumn. Before the insolvency it ran 46 UK stores and employed 975 people. An earlier version of this article credited the brand with £600M of revenue and 1,400 staff and described the episode as a "difficult 2023-2024 restructuring", which badly understated what happened.
What survives of the brand
The brand itself survives. Authentic Brands Group owns the trademark and licenses it, so Ted Baker product still sells through department stores and third-party retailers including John Lewis and House of Fraser. It is included here because readers looking for Britain's best-known clothing brands will expect it, but it has no UK trading revenue to rank. Ray Kelvin founded it in 1988 in Glasgow as a men's shirt shop.
The name "Ted Baker" is entirely fictional. Kelvin chose it so he wouldn't risk his own name if the business failed. The brand is known for subtle humour in the details: hidden labels, unexpected patterns, and irreverent product descriptions.
Segments and markets
Ted Baker covers men's and women's ready-to-wear, accessories, fragrances, and homeware. The brand has expanded to over 50 countries, with a strong presence in the United States and the Middle East. The style blends British formality with eccentric touches.
Sourcing pattern
Under its former owner Ted Baker used Asian production for most of the line with European sourcing for premium pieces. Sourcing now sits with whichever licensee holds the category, so there is no single Ted Baker supply chain to describe, and we have removed a claim that the brand had shifted toward Portuguese production, which we cannot evidence post-administration.
6. Superdry: Is It Japanese or British?
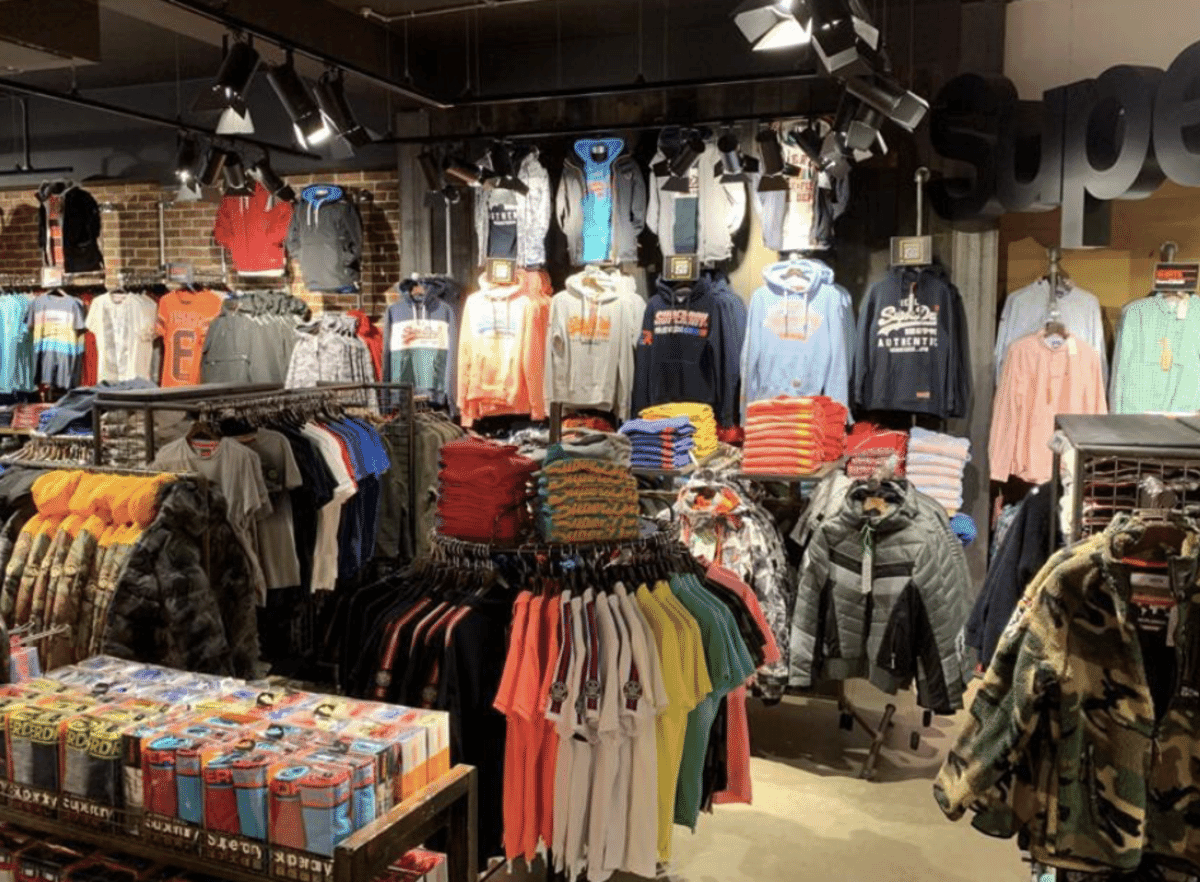
Superdry posts £488.6M (~€572M) in revenue and has 2,200 employees, making it the UK's eighth-largest fashion brand (Superdry PLC, 2025). Despite the Japanese characters on the logo, the brand is 100% British, founded in 2003 by Julian Dunkerton and James Holder in Cheltenham.
The confusion around Superdry's origins is incredibly common. Many consumers assume it's a Japanese label. In reality, the Japanese-inspired aesthetic is purely a design choice, not an indication of where the company comes from.
Style and target audience
Superdry blends vintage American influences with Japanese-inspired graphics. Jackets and hoodies are the top sellers. The brand targets young adults, with prices ranging from £40 to £200.
In recent years, Superdry has doubled down on sustainability. The company has committed to becoming the most sustainable fashion brand on the planet by 2030, an ambitious goal for a company of this size.
Sourcing pattern
Superdry production has shifted toward Turkey and Eastern Europe over the past 5 years, with Portuguese production growing for organic cotton and certified-fabric programs as the sustainability strategy compounds.
9. AllSaints: What Is the Brand Built On?
AllSaints brings in £459.5M (~€538M) in revenue and employs 2,400 people, sitting ninth in the ranking (AllSaints, 2025). Founded in 1994 in London, the brand started as a wholesaler before opening its own stores.
AllSaints shops are instantly recognisable thanks to the vintage sewing machines displayed in their windows, a visual touch that's become a trademark. The style mixes rock influences with relaxed tailoring. Leather jackets (and faux-leather alternatives) are the star product.
Market and expansion
AllSaints runs over 200 stores across 27 countries. The target audience falls between 20 and 40, with a mid-to-high price point. The brand has been steadily expanding its online presence, which now accounts for a significant share of total sales.
Sourcing pattern
AllSaints leather production is primarily in Turkey and Italy. Soft goods (tees, knitwear, sweatshirts) are sourced across Portugal, Turkey, and parts of Asia depending on price tier and certification requirements.
10. Barbour: Why Does It Still Make Coats in England?
Barbour rounds out this ranking with £321.8M (~€376M) in revenue and 1,000 employees, but its cultural influence far exceeds those figures (Barbour, 2025). John Barbour founded the company in 1894 in South Shields, in the northeast of England, and it's become synonymous with waxed jackets.
Barbour originally supplied waterproof clothing to fishermen, sailors, and farmers. The British royal family has worn Barbour for decades and the brand has long held Royal Warrants. Warrants were reviewed and reissued after the accession of King Charles III, so the precise holdings have changed; we have dropped the specific count an earlier version of this article gave, which listed a warrant from "the former Prince of Wales" and did not reflect the review.
From countryside to city
What started as rural workwear has become an urban fashion staple. Barbour waxed jackets are worn on English country estates and city streets alike. The brand still manufactures many items at its original factory in South Shields.
Barbour is also a fascinating case of a family business. It's still owned and managed by the Barbour family, now in its fifth generation. That stability allows for a long-term vision that shows in the consistent quality of the products.
Sourcing pattern
Barbour is unusual on this list for retaining significant UK production. Iconic waxed jackets are still produced at South Shields, and the brand actively markets the British provenance. Soft goods (knitwear, shirts) are sourced internationally including Portugal.
Where Do UK Brands Actually Manufacture?
The big UK brands above have collectively shaped how British fashion is produced and consumed. For emerging UK brands launching in 2026, the patterns they reveal are useful:
Pattern 1: Heritage brands keep some UK production
Burberry (Castleford), Dr. Martens (Wollaston), Barbour (South Shields). The brands with the strongest heritage-quality narratives retain UK production for hero pieces. The premium absorbs the higher cost.
Pattern 2: Premium-mid brands have shifted to Portugal and Italy
Premium-tier UK brands routinely source knitwear, soft goods, and accessories from Portuguese mills. The 5-day truck transit from Porto to London plus EU-tier quality and certifications make Portuguese production structurally favourable for premium-mid positioning.
Pattern 3: Mass-market remains in Asia and Turkey
River Island and similar mid-market chains still source primarily from Bangladesh, China, and Turkey. Portuguese production rarely competes economically below £40 retail (~€47).
Pattern 4: Sustainability-led brands moved earlier
Superdry's pivot to certified fabrics drove their Portuguese sourcing growth. The pattern repeats across UK premium brands: sustainability strategy → certified-fabric requirements → Portuguese mill partnerships.
Realistic Portuguese-produced costs for emerging UK brands
| Garment | CMT €/unit (200 units) | All-in cost €/unit | Typical UK retail (DTC) £ |
|---|---|---|---|
| Heavyweight tee (220 GSM) | €4-€6 | €8-€11 | £35-£70 (~€41-€82) |
| Heavyweight hoodie (350 GSM) | €11-€16 | €17-€27 | £85-£140 (~€100-€164) |
| Wool overshirt | €18-€28 | €35-€55 | £150-£250 (~€176-€293) |
| Tailored blazer | €28-€42 | €55-€85 | £250-£420 (~€293-€493) |
| Waxed jacket (Barbour-adjacent) | €35-€55 | €70-€110 | £280-£480 (~€328-€562) |
Sources: PCF aggregated factory quotes 2024-2026.
Which UK-Style Approach Fits Which Founder?
Different founder types match different UK-fashion approaches. From our placement records:
| Founder archetype | Best UK-style approach | Why |
|---|---|---|
| Heritage / craft-focused | Barbour-style with UK or PT factory partnership | Quality-led narrative |
| Subculture-driven | Dr. Martens-style cultural alignment | Authenticity over hype |
| Premium contemporary | Burberry / McQueen-style premium positioning | Retail tier supports premium |
| Tailoring-led | Ted Baker / Filippa K hybrid | British formality with twist |
| Luxury footwear | Jimmy Choo-style premium positioning | Italian production preferred |
| Affordable fashion | River Island-style fast turnover | Asia + Turkey sourcing |
| Sustainability-led | Superdry-pivot-style certified materials | Portugal grows with this strategy |
| Streetwear-adjacent | AllSaints-style rock-influenced | Mid-tier €/£ retail |
| Provocative / avant-garde | McQueen-style theatrical | Fashion-week scheduling |
Founder archetypes are a pattern we see in incoming briefs from UK brands, not a survey. The named brands are reference points for a positioning, not claims about how those companies operate.
If you recognise yourself, lean toward your archetype's approach unless you have a specific reason not to.
What Mistakes Do Emerging UK Brands Make?
Five years of placement records surface a recurring set of mistakes for emerging UK brands sourcing internationally:
- Trying to compete with River Island on price. Mass-market UK pricing requires Asian-volume scale that emerging brands can't match. Compete on positioning, not price.
- Forgetting post-Brexit customs realities. UK to EU shipping requires customs declarations and VAT handling. Brands sourcing in Portugal need to factor 30-60 minute longer customs processing vs pre-Brexit.
- Skipping certifications for premium positioning. Above £80 retail, UK customers increasingly check for OEKO-TEX, GOTS, or B Corp. Brands without verifiable certifications face friction.
- Underestimating shipping cost from Portugal. UK delivery from Portugal: €0.80-€1.50 per unit on bulk freight, €4-€8 per unit on small consignments. Plan accordingly.
- Not registering trademark with UK IPO and EUIPO. Post-Brexit, UK and EU registrations are separate. UK IPO costs £170 minimum; EUIPO €850. Brands skipping one face exposure on either side.
- Choosing factory tier wrong. First UK launches at 100-200 units belong at Portuguese specialist factories. Large export-tier factories optimised for 1,000+ unit orders ignore or over-quote small briefs.
- Ignoring the August Portuguese factory shutdown. Most Portuguese factories close 2-3 weeks in mid-August. UK AW launches need fabric locked by mid-July.
- Imitating Burberry without resources. Heritage British brands have 100+ years of equity. Emerging brands attempting heritage positioning without distinctive product fail consistently.
Running into production issues? Get in contact and tell us what you're making. We're a group of Portuguese factories and we answer every serious brief within 24 hours.
How Does the August Shutdown Affect UK Brands?
Most Portuguese factories close 2-3 weeks in mid-August. UK brands targeting AW season drops are particularly affected because production typically peaks in July-August. If your timeline crosses early-to-mid August:
- Lock fabric and trim sourcing by mid-July
- Sample rounds across August add 4-5 weeks vs October cycles
- AW drops shipping early September must clear bulk by late July
- Add 1-2 days for post-Brexit UK customs processing on bulk shipments
UK brand teams new to Portuguese sourcing routinely underestimate the August gap. Build it into your launch calendar from day one.
What Do These Brands Have in Common?
The nine of these brands still trading in the UK generate roughly £7.2 billion of revenue between them and employ about 34,000 people, summed from the figures in the table above. Because their fiscal years differ, that total is an approximation rather than a measured aggregate.
What connects these brands is their ability to turn tradition into contemporary relevance. Burberry reinvented itself for the digital era. Dr. Martens went from a work boot to a cultural symbol. Barbour brought rural clothing into the city.
Longevity is survived, not enjoyed
For anyone working in textiles, these brands offer lessons in longevity, identity and adaptation. Five are over 75 years old and three have passed the century mark. They are not all still growing, though, and it would be misleading to say so: Ted Baker's UK retail business is gone, River Island lost £65.3M at operating level in 2024 before returning to a £11.6M pre-tax profit in 2025, and Burberry spent two years in a turnaround before its FY2026 recovery. Longevity in this industry is survived rather than enjoyed.
Talk to our team: Building a UK brand and considering Portuguese production? Get in contact and we'll place your production with Portuguese factories that understand UK market expectations.
Related: the biggest French clothing brands
Frequently Asked Questions
What people ask about British clothing brands: which is biggest, whether any still manufacture in the UK, which sell internationally, and what happened to the names that have disappeared from the high street.
What's the biggest clothing brand in the UK?
Burberry, with £2.42bn of revenue in the year to 28 March 2026 (about €2,830M). Founded in 1856, it is famous for the check pattern and the trench coat, and its turnover is nearly 2.7 times the runner-up, Clarks.
Do British fashion brands manufacture in the UK?
It depends on the brand. Barbour maintains significant production in South Shields, England. Burberry produces some items in British factories, including its trench coats. Dr. Martens has the Wollaston Made in England line. Most other brands, especially fast-fashion names like River Island, outsource production to factories in Asia, Turkey, and Eastern Europe.
Which of these brands sell internationally?
All of them have international reach, at minimum through e-commerce. Burberry, Dr. Martens, and Jimmy Choo have retail locations in major cities worldwide. River Island and Superdry sell through their online stores to global markets. Clarks has authorised multi-brand retailers in numerous countries.
What makes British fashion different from other European traditions?
British fashion combines three elements: a strong tailoring tradition (Savile Row), subcultural influence (punk, mod, grime), and unapologetic eccentricity. While Italian fashion favours understated luxury and French fashion leans toward elegance, British fashion tends to be bolder and more irreverent. According to the British Fashion Council, this diversity is the sector's greatest asset.
Are British brand pieces worth the investment?
In terms of durability, brands like Barbour, Dr. Martens, and Clarks offer products built to last for years. A Barbour waxed jacket can last over a decade with proper care. For luxury pieces, Burberry and Alexander McQueen hold strong resale value on the secondhand market.
Can a new UK brand realistically produce in Portugal?
Yes, easily. Portuguese factory MOQs of 100-300 units per style align well with first-collection UK brand volumes. The 5-day truck transit from Porto to London makes Portugal one of the most logistically convenient EU sourcing options for UK brands. Post-Brexit, customs processing adds 30-60 minutes per shipment but doesn't fundamentally change the economics.
What's the realistic launch budget for an emerging UK brand?
Production-only investment for a 6-piece UK-positioned capsule produced in Portugal: £15,000-£40,000 (~€17,500-€47,000). All-in (including branding, photography, e-commerce, launch marketing): £30,000-£75,000 (~€35,000-€88,000). Brands launching below £30,000 all-in typically have either marketing or production undercooked.
How does Brexit affect UK brand sourcing in Portugal?
UK to EU shipping now requires customs declarations and VAT handling. Practical impact: 30-60 minute processing delay, plus paperwork. Brands using established freight forwarders (DHL, FedEx, UPS) handle the customs side smoothly. Total Brexit-driven cost addition: €0.30-€0.80 per unit on bulk freight, manageable across most price tiers.
Should I copy the heritage strategy of Burberry or Barbour?
Heritage strategy works only with genuine heritage. Emerging brands without 50+ years of history cannot credibly claim heritage positioning. Better strategies: distinctive product (subcultural like Dr. Martens), category specialisation (technical like Barbour's waxed jackets), or community-led identity (modern like AllSaints). Heritage is the hardest moat to fake.
What's the certification requirement for UK retail?
For retail above £80 (~€94), expect customers to look for OEKO-TEX, GOTS, B Corp, or similar. Below £40 (~€47), certifications matter less but the Green Claims Directive (which applies in EU markets, increasingly mirrored by UK CMA) penalises vague sustainability claims regardless of price tier. Specific, certified language is the safe approach.
We're a group of 80 documented Portuguese clothing factories based in Porto and Guimarães. Tell us your product, volume, and timeline. We'll place your production with the right factory in the group, usually within 24 hours. You work directly with the factory. No commissions, no pitch, no upsell.
Get in contact Download the directory (€39)Need a tech pack? Get a factory-ready single-style tech pack for €79. See what's included.
Sources
- Burberry Annual Report 25/26. Revenue of £2.42bn for the year to 28 March 2026, adjusted operating profit £160M.
- Capri Holdings, fiscal 2025 results. Jimmy Choo revenue of US$605M for the year to 29 March 2025, against US$618M in fiscal 2024. Reported in US dollars, which is the source of the currency error corrected on this page.
- Dr. Martens plc, Superdry, Clarks, AllSaints and Barbour company reporting, plus Companies House filings for the privately held companies. Fiscal years differ, so the ranking is not like-for-like.
- Kering. Alexander McQueen sits in the "Other Houses" segment and is not separately disclosed, so the McQueen figure on this page is an estimate and labelled as one.
- Ted Baker: No Ordinary Designer Label Limited, the holding company for Ted Baker's UK and European retail, entered administration in March 2024 and all UK and Ireland stores closed by autumn 2024. It operated 46 UK stores employing 975 people before the insolvency. The trademark is owned and licensed by Authentic Brands Group.
- UKFT Industry Footprint Report. UK fashion and textile industry contribution of about £62bn to GDP and 1.3 million jobs, equivalent to £1 in every £34 of gross value added. A later Oxford Economics estimate puts it near £67.5bn. Both are fashion and textiles combined, a wider basis than the British Fashion Council's fashion-only figure.
- PCF quoting records 2024-2026 across the 80 factories in our group. Source for the Portuguese production costs and the first-run budget range. PCF has placed brands since 2021, including UK-based brands; the sourcing-pattern observations are ours, not the brands' disclosures.
- Removed rather than re-sourced: a £35bn industry contribution attributed to the British Fashion Council, Ted Baker revenue of £600M and 1,400 staff, Burberry revenue of £2,000.5M, Jimmy Choo revenue stated in pounds when the source reports dollars, a combined employee total credited to the British Fashion Council when it was summed from this page's own table, a specific Royal Warrant count for Barbour that predated the post-accession review, and a claim that all ten brands are still growing.
Related reading
- Top 10 Portuguese clothing factories
- Nearshoring fashion production to Portugal
- Sustainable fabrics guide
- Top 10 clothing brands in France
- Red flags when picking a manufacturer
- MOQ minimums in Portugal
- Clothing manufacturing costs in Portugal
- How to find a clothing manufacturer